Multivariate normal distribution
Generalization of the one-dimensional normal distribution to higher dimensions
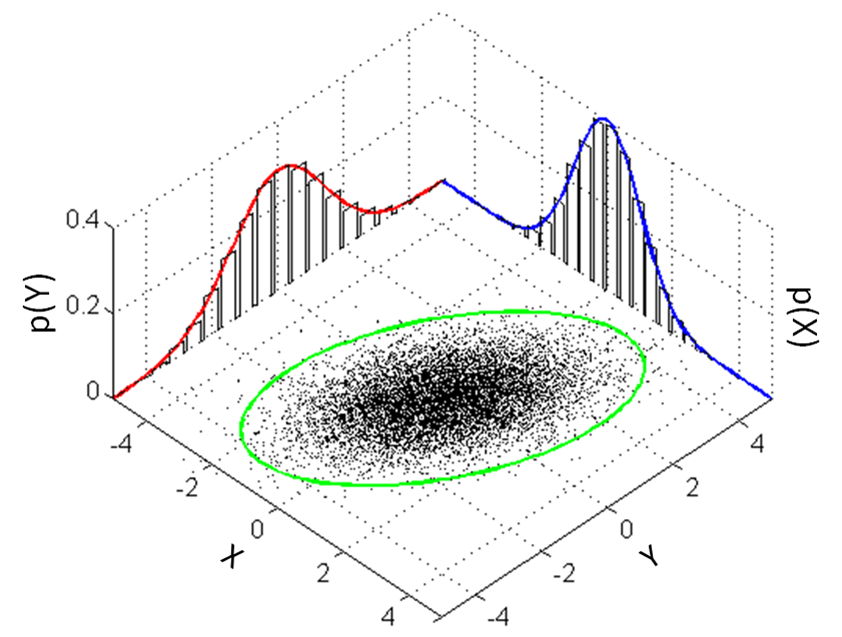
In probability theory and statistics, the multivariate normal distribution, multivariate Gaussian distribution, or joint normal distribution is a generalization of the one-dimensional (univariate) normal distribution to higher dimensions. One definition is that a random vector is said to be k-variate normally distributed if every linear combination of its k components has a univariate normal distribution. Its importance derives mainly from the multivariate central limit theorem.
From Wikipedia, under CC BY-SA. More on occurri.